
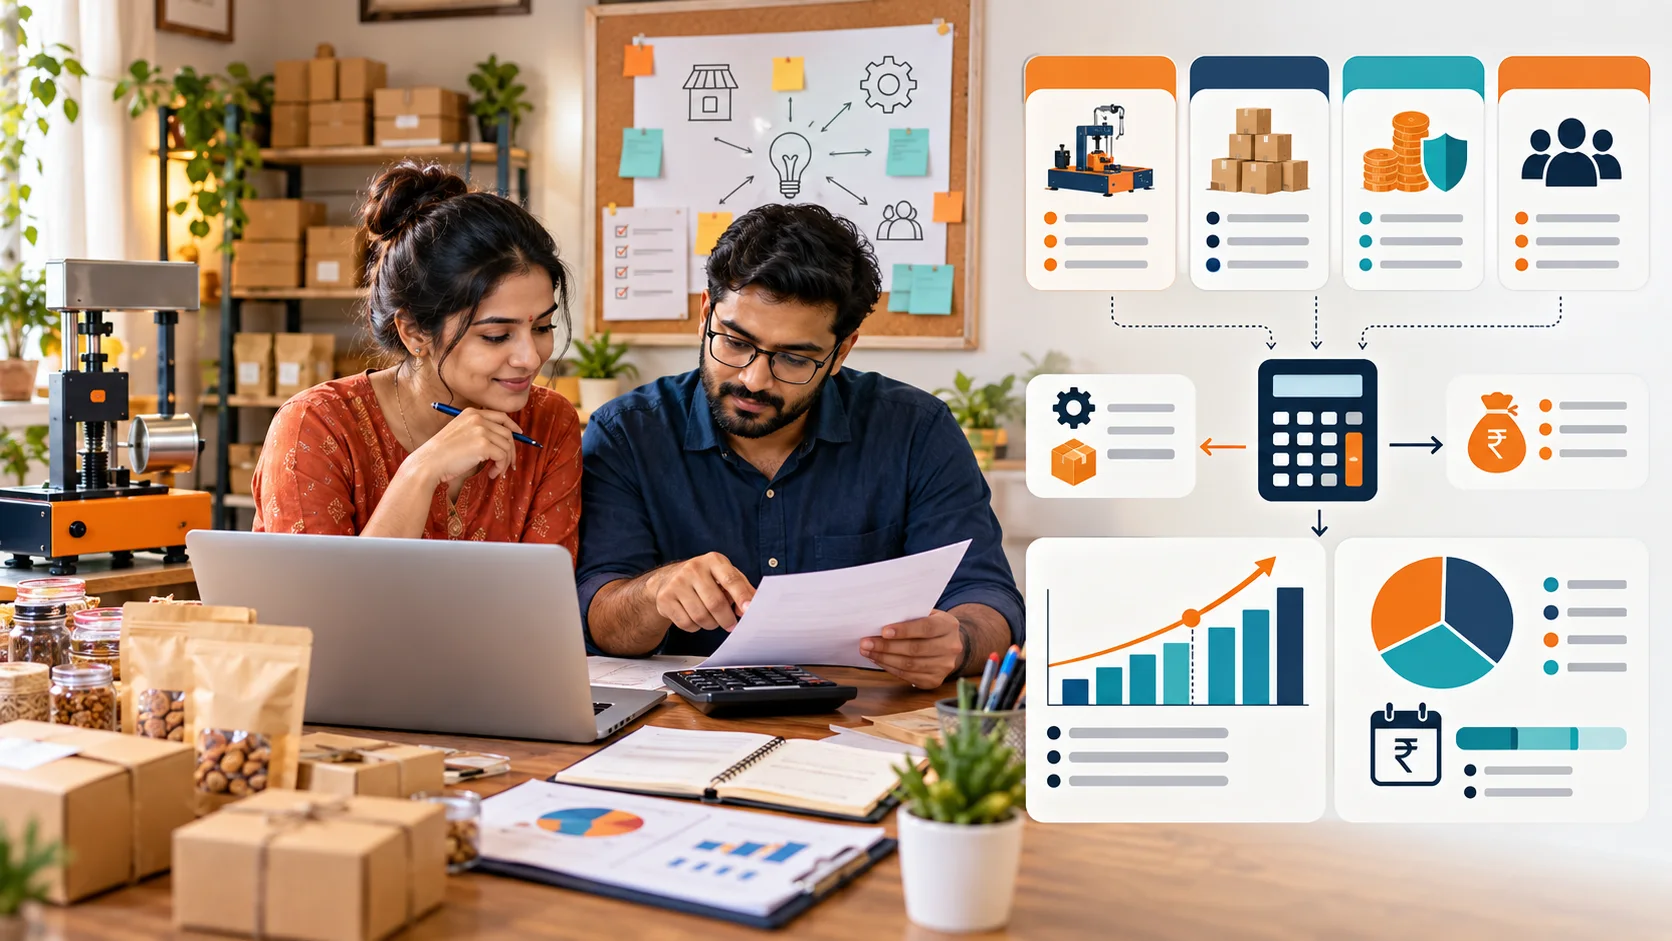
Home Business के लिए कितना पैसा चाहिए? Budget, Break-even और Loan Readiness Guide 2026
Home business का startup budget, working capital, equipment ROI, break-even, cash buffer और responsible loan readiness calculate करने की detailed Hindi guide।
Home business की funding जरूरत “कौन-सा idea है?” से कम और “उस idea को किस scale पर कैसे deliver करेंगे?” से ज्यादा तय होती है। Content writer existing laptop से शुरू कर सकता है, जबकि product photographer को light, camera और backdrop चाहिए। Tiffin business में kitchen equipment के साथ daily ingredients और delivery cash चाहिए। Handmade seller को मशीन से ज्यादा inventory और returns रोक सकते हैं।
इस guide का उद्देश्य loan बेचने या कोई earning promise करना नहीं है। यहां startup cost को सही buckets में बांटना, small paid pilot से budget verify करना, equipment खरीदने से पहले outsourcing compare करना और debt लेने से पहले repayment stress test करना सिखाया गया है। Interest, fees, schemes और eligibility बदल सकती हैं; current official documents और qualified financial advice verify करें।
सबसे पहले पांच capital buckets बनाएं
| Bucket | Examples | Common mistake |
|---|---|---|
| One-time setup | Basic tools, device, furniture, initial compliance | हर possible feature launch पर खरीद लेना |
| Working capital | Materials, packaging, courier, wages, payment gap | Setup budget में daily cash need भूलना |
| Customer acquisition | Samples, portfolio, local outreach, limited ads | Logo पर खर्च, customer test पर नहीं |
| Compliance and quality | Licences, testing, labels, bookkeeping, safety | Optional मानकर बाद के लिए छोड़ना |
| Contingency reserve | Refund, repair, slow month, supplier delay | सारा cash inventory में lock करना |
हर item के सामने तीन labels लगाएं: must have now, after paid demand और not required. इस एक exercise से inflated startup budget काफी कम हो सकता है।
Startup budget formula
Required launch cash = setup cost + first-cycle working capital + compliance cost + customer-acquisition test + contingency reserve − available reusable assets
Reusable asset का मतलब zero cost नहीं है। Existing laptop, mixer, camera या room का maintenance, electricity, wear और replacement allocation operating cost में रखें। Personal emergency savings को automatically business capital न मानें।
Different home-business models की cash profile
| Model | Cash कहां लगता है? | सबसे बड़ा risk |
|---|---|---|
| Digital service | Device, software, portfolio, internet | Unpaid proposals and revisions |
| Teaching or consulting | Equipment, room setup, lead generation | No-shows and preparation time |
| Food subscription | Ingredients, containers, delivery, hygiene | Wastage and daily working capital |
| Handmade product | Tools, raw material, packing | Founder labour underpriced |
| Reselling | Inventory, shipping, returns | Cash blocked in slow stock |
| Product photography | Lighting, backdrop, camera, storage | Equipment bought before clients |
Home-business ideas और operational fit समझने के लिए AFShop की Home Operations Guide देखें। Broader opportunity comparison के लिए 36 Small Business Ideas guide उपलब्ध है।
Estimate नहीं, vendor-backed budget बनाएं
- हर equipment और material के कम-से-कम two comparable quotations लें।
- Price में tax, installation, shipping, accessories और warranty check करें।
- Monthly software को annual headline discount से पहले cash-flow basis पर देखें।
- Consumable yield निकालें: one pack से कितने saleable units बनेंगे?
- Defect, wastage और sample use का percentage जोड़ें।
- Courier remote-area, return-to-origin और damage risk अलग estimate करें।
- Budget date लिखें; पुराने quotation को current cost न मानें।
Working capital cycle कैसे calculate करें?
Cash conversion cycle = inventory days + customer receivable days − supplier credit days
Home seller cash order से पहले material खरीद सकता है, delivery के बाद platform settlement पा सकता है और return window तक uncertainty रख सकता है। इसी gap को working capital fund करता है।
Simple 30-day forecast
| Week | Opening cash | Expected collection | Committed outflow | Closing cash |
|---|---|---|---|---|
| 1 | Available balance | Advance or confirmed receipts | Materials, packaging, fees | Opening + inflow − outflow |
| 2 | Previous closing | Realistic collections | Delivery, software, replenishment | Updated balance |
| 3 | Previous closing | Do not include uncertain leads | Refund and repair reserve | Updated balance |
| 4 | Previous closing | Settlement dates considered | Statutory and monthly obligations | Month-end balance |
Sales pipeline को cash collection न मानें। Only contracted or reasonably expected receipts रखें और late-payment scenario अलग बनाएं।
Emergency buffer कितना रखें?
Universal percentage सही नहीं है। तीन scenarios बनाएं:
- Operating interruption: equipment repair या internet/power backup.
- Revenue delay: one settlement cycle late या client invoice delayed.
- Quality event: refund, rework, damaged batch or return.
Minimum buffer इन scenarios में सबसे plausible short-term cash gap cover करे। Personal household emergency fund को business refund reserve के साथ mix न करें।
Equipment खरीदें, rent करें या outsource?
| Question | Buy | Rent/shared | Outsource |
|---|---|---|---|
| Demand frequency | Stable and frequent | Periodic | Uncertain or low |
| Quality control | In-house critical | Shared control acceptable | Vendor specification reliable |
| Cash requirement | Highest upfront | Moderate | Per-order variable |
| Capacity risk | Idle machine | Slot availability | Vendor delay or dependency |
| Best stage | Proven volume | Growing test | Early validation |
Equipment payback orders = net equipment investment ÷ per-order saving versus outsourcing
अगर payback orders practical 12–18 month demand से ज्यादा हैं या machine home safety/space disturb करती है, outsource बेहतर हो सकता है। Resale value को guaranteed न मानें।
Break-even सही तरीके से निकालें
Contribution per completed order = net revenue − direct material − direct labour − packaging − delivery − selling/payment fee − expected refund or rework cost
Monthly break-even orders = monthly fixed cost ÷ contribution per completed order
Example: अगर fixed cost ₹15,000 और contribution ₹300 है, तो accounting break-even 50 completed orders है। लेकिन founder की desired salary fixed cost में नहीं है तो business household income goal पूरा नहीं करेगा। इसलिए दो break-even बनाएं:
- Operating break-even: business costs cover हों।
- Household-sustainable break-even: business costs + founder compensation cover हो।
Three-case budget stress test
| Scenario | Sales assumption | Cost assumption | Purpose |
|---|---|---|---|
| Conservative | Expected orders से 30–50% कम | Returns and acquisition cost higher | Survival and debt affordability |
| Base | Paid pilot evidence के अनुरूप | Vendor-backed cost | Operating plan |
| Upside | Capacity के भीतर higher demand | Overtime or replenishment included | Growth requirement |
Loan repayment केवल upside scenario में possible है तो loan affordable नहीं माना जाना चाहिए।
Loan readiness scorecard
हर “yes” के लिए one point दें:
- कम-से-कम कुछ paid demand या repeat orders का evidence है।
- Loan का exact use और vendor quotation available है।
- Contribution per order positive और documented है।
- Conservative cash flow EMI के बाद positive रहता है।
- Household essential expenses loan repayment पर depend नहीं हैं।
- Existing debt और credit obligations list किए हैं।
- APR, fees, security, penalty और prepayment terms समझे हैं।
- Repayment से पहले emergency buffer बचता है।
- Equipment failure or demand drop का backup है।
- Business and personal records अलग हैं।
Low score पर loan application से पहले business evidence और cash-flow discipline improve करें। यह lender approval model या financial advice नहीं है।
EMI affordability का conservative test
Debt-service buffer = conservative monthly business cash available after operating costs ÷ total monthly business debt payments
Ratio जितना 1 के करीब होगा, उतना छोटा shock repayment disrupt कर सकता है। Personal household income को तभी जोड़ें जब वह वास्तव में stable, available और legally/financially appropriate हो। Lender eligibility और your affordability अलग concepts हैं—approval मिलने का मतलब loan safe होना नहीं है।
Loan offer compare करते समय क्या देखें?
RBI guidance Key Facts Statement में critical loan information और cost transparency पर जोर देती है। केवल monthly EMI या advertised interest rate compare न करें।
- Annual Percentage Rate or all-inclusive cost
- Interest fixed है या floating
- Processing, documentation and other charges
- Insurance or bundled service optional/mandatory status
- Penal charges and delayed-payment treatment
- Security, guarantee or lien
- Prepayment and foreclosure conditions
- Disbursement amount versus sanctioned amount
- Repayment schedule and total amount payable
- Grievance-redressal contact
Blank documents sign न करें, unofficial agent account में fee न भेजें और lender/regulated entity identity verify करें। Digital loan में app permissions और data use भी पढ़ें।
Own savings, advance, supplier credit या debt?
| Source | Strength | Risk/control |
|---|---|---|
| Founder savings | No repayment schedule | Household emergency fund protect करें |
| Customer advance | Demand proof and working capital | Refund, delivery and scope terms clear रखें |
| Supplier credit | Cash cycle छोटा हो सकता है | Late payment relationship and pricing impact |
| Friends/family | Flexible हो सकता है | Written loan/equity terms और relationship risk |
| Formal loan | Structured capital | Interest, fees, repayment and credit risk |
| Grant/subsidy scheme | Eligible support | No guarantee; official eligibility and process |
Government schemes को कैसे verify करें?
Scheme name सुनकर eligibility assume न करें। Ministry of MSME official portal PMEGP, CGTMSE और other support programmes list करता है। PMEGP official portal new viable microenterprises के लिए objectives और conditions देता है, लेकिन application bank appraisal, eligibility, guidelines और prohibited activity checks के अधीन हो सकती है।
- Only official government or implementing-agency portal खोलें।
- Latest guideline date और applicant category check करें।
- Project type, location, education, existing-unit and subsidy conditions पढ़ें।
- Subsidy को immediate free cash न मानें; process and bank terms समझें।
- Agent के guaranteed sanction claim से सावधान रहें।
- Application receipt और communication records रखें।
Project report में क्या होना चाहिए?
- Business problem, customer and offer
- Paid-pilot or demand evidence
- Founder skill and delivery capacity
- Vendor-backed setup budget
- 12-month conservative sales and cash-flow assumptions
- Contribution, fixed cost and break-even
- Working-capital cycle
- Compliance and risk controls
- Funding source and use
- Repayment plan and downside response
Round-number sales growth और unsupported margin project report को reliable नहीं बनाते। Assumption के पास evidence source या calculation लिखें।
30-day budget validation plan
Days 1–7: cost map
- Five capital buckets बनाएं।
- Must-have और later purchases अलग करें।
- Two vendor quotations लें।
- Personal emergency savings ring-fence करें।
Days 8–14: paid pilot
- Outsourced/shared tools से three to ten paid orders deliver करें।
- Actual time, material, delivery and defect cost log करें।
- Customer advance and refund process test करें।
- Contribution calculation update करें।
Days 15–21: scenario model
- Conservative, base and upside cash flow बनाएं।
- Operating and household-sustainable break-even निकालें।
- Equipment payback versus outsourcing compare करें।
- Buffer need calculate करें।
Days 22–30: funding decision
- Loan readiness scorecard complete करें।
- Official schemes and eligible lenders verify करें।
- KFS and all-inclusive cost compare करें।
- Loan, smaller launch, outsource या wait decision evidence से लें।
Common funding mistakes
- Demand proof से पहले machine खरीदना।
- Working capital को setup budget में भूलना।
- Personal emergency savings पूरा business में लगाना।
- Sales को cash collection और revenue को profit मानना।
- Founder labour zero price करना।
- EMI को केवल upside sales से affordable दिखाना।
- Interest rate देखना, APR and fees नहीं।
- Subsidy या loan sanction guaranteed मानना।
- Multiple loan applications बिना comparison करना।
- Old losses को model fix किए बिना new debt से fund करना।
Final takeaway
Home business का सही startup budget internet list से नहीं, paid pilot और vendor-backed cost sheet से निकलता है। पहले must-have setup, working capital, compliance, customer acquisition और contingency अलग करें। Equipment खरीदने से पहले rental or outsourcing compare करें और operating के साथ household-sustainable break-even भी निकालें।
Debt growth tool हो सकती है, demand substitute नहीं। Conservative cash flow repayment support करे, total cost समझ में आए और shock के बाद buffer बचे—तभी formal funding evaluate करें। RBI, Ministry of MSME, PMEGP और Udyam के official resources से current information verify करें; guaranteed approval or subsidy के private claims पर निर्भर न रहें।
Sources and verification
- RBI regulatory handbook — Key Facts Statement and fair-practice guidance for retail and MSME term loans.
- RBI customer-service notification — APR comparison and Key Fact Statement transparency guidance.
- Ministry of MSME schemes and services — official overview of PMEGP, CGTMSE and other MSME support programmes.
- Official PMEGP portal — current scheme objectives, beneficiary conditions and application information.
- Official Udyam Registration Portal — official registration process and warning against unofficial portals.
This article provides educational budgeting frameworks, not lending, investment, legal, tax or accounting advice. Eligibility, interest, fees, programme limits and regulations can change. Verify current official documents and obtain suitable professional advice before borrowing or investing.
Found an error? Review our Corrections Policy or contact the editorial team.
Article at a glance
| Written by | Amit Kumar |
|---|---|
| Published | 01 Oct 2026, 12:42 AM IST |
| Reading time | 9 minutes |
| Topic | Ecommerce research and practical guidance |
Frequently Asked Questions
Home business शुरू करने के लिए कितना पैसा चाहिए?
कोई universal amount नहीं है। Required cash setup, first-cycle working capital, compliance, customer-acquisition test और contingency reserve पर depend करता है। Existing reusable assets और paid pilot के actual costs से budget बनाएं।
Working capital और setup cost में क्या अंतर है?
Setup cost tools, equipment और initial installation जैसे one-time खर्च हैं। Working capital materials, packaging, delivery, wages और collection delay के बीच daily operations चलाता है।
Equipment खरीदना बेहतर है या outsource करना?
Early unproven demand में outsourcing cash risk कम करती है। Stable frequent demand, critical quality control और practical payback orders होने पर buying sensible हो सकती है। Rental or shared facility भी middle option है।
Home business का break-even कैसे निकालें?
Monthly fixed costs को contribution per completed order से divide करें। Founder compensation शामिल और exclude करके operating तथा household-sustainable break-even अलग निकालें।
Loan लेने से पहले क्या check करें?
Paid demand, positive contribution, exact use, vendor quotation, conservative cash flow, emergency buffer और existing obligations check करें। EMI केवल optimistic sales में affordable हो तो loan high risk है।
Loan offer में APR क्यों देखना चाहिए?
APR या all-inclusive cost headline interest के अलावा applicable charges को बेहतर comparison में ला सकती है। Key Facts Statement में rate, fees, penalty, repayment और other critical terms पढ़ें।
क्या PMEGP subsidy guaranteed होती है?
नहीं। Official eligibility, project viability, guidelines, bank appraisal और other conditions लागू हो सकती हैं। Only official portal use करें और guaranteed sanction claims से सावधान रहें।
Emergency buffer कितना होना चाहिए?
Equipment repair, one settlement delay और refund or rework जैसे plausible short-term gaps calculate करें। Business buffer को household emergency fund से अलग रखें।
Customer advance लेना सही है?
Advance demand और working capital support कर सकता है, लेकिन deliverable, timeline, cancellation और refund terms स्पष्ट लिखें तथा amount को unrelated personal खर्च में use न करें।
Loan approval और affordability क्या एक ही हैं?
नहीं। Lender eligibility के आधार पर loan approve कर सकता है, लेकिन business owner को conservative cash flow, total cost, household obligations और downside risk से affordability अलग assess करनी चाहिए।
Amit Kumar
Consumer Education WriterAmit creates independent consumer education guides about comparing prices, merchant terms and important purchase conditions.
View author profileRead More Blogs
Meesho Dropshipping 2026: बिना Heavy Inventory Selling कैसे शुरू करें?
Meesho पर low-inventory selling का practical Hindi guide: seller registration, supplier selection, stock sync, catalog, packing, returns, unit economics और compliant scaling।
23 · Read blog
Zomato Orders क्यों नहीं बढ़ रहे? Impression से Repeat Order तक Complete Funnel Guide
Zomato orders बढ़ाने के लिए impression, menu open, cart, accepted order, delivery, contribution और repeat customer का complete data-driven funnel समझें।
16 · Read blog
India के 30 Best Online Selling Platforms: Sellers के लिए Complete 2026 Guide
India में products online बेचने के लिए 30 marketplaces, niche channels, B2B networks, social commerce और own-store platforms की practical Hindi comparison।
14 · Read blog
Customers कैसे पाएं? First 100 Customers की Acquisition Guide 2026
Small business के लिए customers पाने की practical Hindi guide: ICP, offer, outreach, referrals, partnerships, content, sales pipeline, CAC और 90-day roadmap।
9 · Read blog
Comments 0
No comments yet. Be the first to share a useful thought.
Leave a comment
Your email address will not be published. Comments are reviewed before appearing. Web addresses are displayed as plain text and are never clickable.